
Florida homeowners facing pipe bursts, roof leaks, or storm damage must stop the water source, document losses, and notify insurers within 24 hours. Mitigation delays weaken claims. Denied or underpaid claims often require legal action. Charles Injury Law helps South Florida property owners in Plantation and Fort Lauderdale pursue full compensation through aggressive, trial-ready representation.
Key Takeaways
- Contact your insurance company within 24 hours of discovering water damage to protect your claim eligibility.
- Document all damage with photographs and written descriptions before beginning any cleanup or restoration work.
- Florida’s hurricane season runs June through November, creating peak water damage risk for homeowners statewide.
- Stop the water source immediately to prevent additional damage and demonstrate reasonable care to your insurer.
What Do You Need Before Filing Your Claim?
Solid documentation determines whether a Florida homeowner recovers full compensation or fights a denial for months. Water damage ranks as the single most common homeowner insurance claim filed in Florida. It remains one of the most misunderstood. Insurance companies aggressively defend against payouts, scrutinizing every detail before releasing funds. Homeowners in Plantation, Fort Lauderdale, and across Broward County need a clear file ready before making that first call.
What paperwork should a homeowner gather first?
Start with the insurance policy itself, then build outward. A complete file protects against lowball offers and unwarranted denials.
- Full homeowner’s insurance policy, including endorsements and exclusions
- Date-stamped photos and video of every affected room
- Repair estimates from licensed contractors
- Receipts for emergency mitigation work already completed
- Written notes on when the damage started and how it spread
Does the type of water matter for the claim?
Yes. Distinguishing flood versus water damage matters because standard homeowner policies rarely cover flood events without a separate flood policy. Sudden pipe bursts and roof leaks typically fall under standard coverage. Rising water from outside the home often does not.
A skilled water damage lawyer fort lauderdale homeowners trust reviews policy language before a single form goes to the carrier. Charles Injury Law prepares every case as though it will reach trial, fighting to maximize compensation throughout Fort Lauderdale and Broward County, with direct familiarity with South Florida disputes from its Plantation base.
How Do You File a Florida Water Damage Claim?
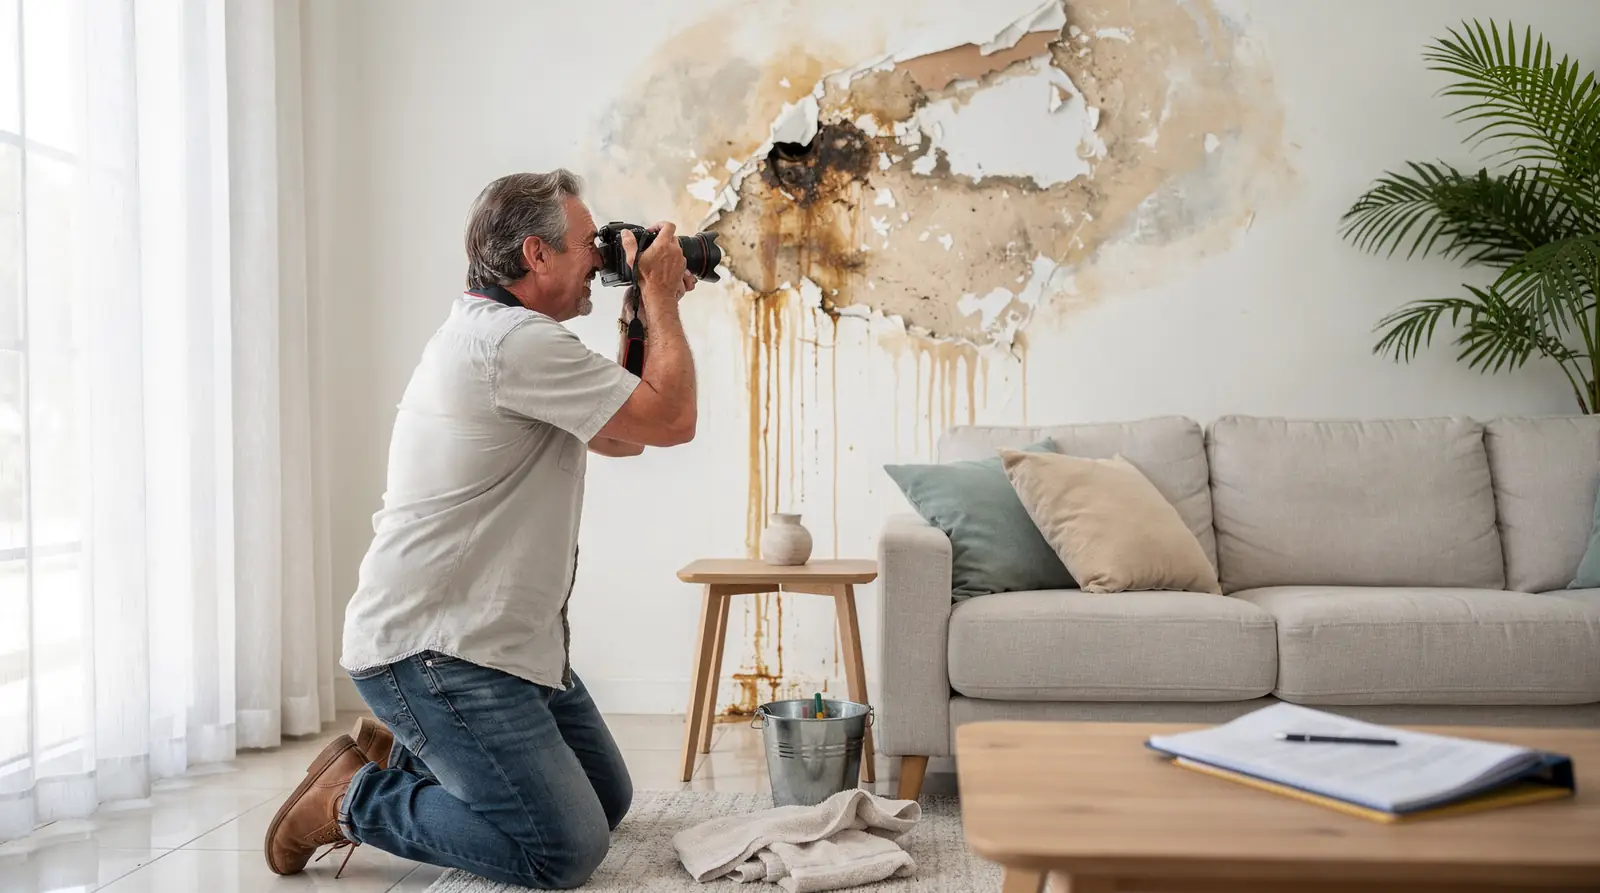
Filing a Florida water damage claim starts with stopping the water source, documenting the damage, and notifying the insurer within 24 hours. Homeowners in Plantation, Fort Lauderdale, and across South Florida cannot afford to wait for an adjuster before taking action. Every hour of delay risks mold growth, additional structural damage, and a weaker case for full payout. The process matters as much as the timing, since insurers scrutinize gaps in documentation and use them to reduce settlements.
Property owners should follow these steps in order:
- Shut off the water source or affected supply line to prevent further intrusion.
- Photograph and video every damaged area, including soaked flooring, drywall, and personal belongings.
- Call the insurance company within 24 hours to open the insurance water claim.
- Keep receipts for emergency mitigation, temporary repairs, and displacement costs.
- File formal notice with the insurer well before Florida’s filing deadline.
Does Flood Insurance Cover the Same Damage as a Homeowner’s Policy?
No. Flood versus water damage coverage depends entirely on the source of the water. Standard homeowner’s policies typically cover sudden, internal water events like burst pipes. Flood insurance covers rising water from outside the home. Misidentifying the category leads to unnecessary denials.
What If the Insurer Disputes the Claim?
Insurers frequently dispute cause, timing, or scope of damage to limit payouts. An experienced Fort Lauderdale water damage attorney knows how to navigate these disputed insurance structures and hold responsible parties accountable. Charles Injury Law provides full-service representation, from investigation through settlement, fighting for the maximum compensation each homeowner deserves.
What Mistakes Could Delay or Deny Your Claim?
Cleaning up a flooded Plantation kitchen before snapping a single photo destroys the proof an insurer needs to pay out. Delaying mitigation ranks among the top reasons Florida water damage claims get denied altogether. Homeowners rushing to dry a soaked living room often toss ruined carpet or drywall without documentation, leaving adjusters nothing to verify.
Why does water classification matter for insurance approval?
Insurers treat clean, gray, and black water differently, and that classification drives both cleanup cost and coverage decisions. A burst supply line produces clean water. A sewage backup or storm surge introduces contamination that raises remediation costs and invites closer scrutiny. Misidentifying the category on a claim form can trigger delays or outright denial.
Common missteps that sink Florida claims include:
- Skipping photos and video before cleanup begins
- Waiting days to report the loss or start drying
- Downplaying or mislabeling the water source
An experienced water damage lawyer fort lauderdale homeowners trust catches these errors early, much like retaining counsel immediately after a serious accident changes outcomes. Charles Injury Law’s attorneys aggressively push back against insurers to recover full compensation owed to Florida property owners.
FAQ
How soon do you need to notify your insurer after water damage?
Florida homeowners must contact their insurance company within 24 hours of discovering water damage. Mitigation delays weaken claims, so prompt notification protects claim eligibility and demonstrates reasonable care to the insurer.
What documentation supports a strong water damage claim?
Gather the full insurance policy, date-stamped photos and video of every affected room, licensed contractor repair estimates, mitigation receipts, and written notes on when the damage started and spread.
Does homeowners insurance cover all types of water damage?
No. Standard policies typically cover sudden pipe bursts and roof leaks, while rising water from outside the home falls under flood coverage, which requires a separate flood policy.
Conclusion
In closing, navigating a water damage claim demands vigilance, documentation, and unwavering advocacy for your rights as a Florida homeowner. The path from initial loss to full compensation requires strategic action and expert guidance to counter insurance company resistance. Your property deserves protection, and your claim deserves aggressive pursuit. When water damage strikes, securing experienced legal representation ensures you recover the maximum compensation your loss truly demands, not just what insurers initially offer.