
People searching how long do slip and fall settlements take often want a clear date or number of weeks. There is no standard timeline. A claim may move at different speeds depending on the injury and treatment, the evidence, questions about notice and responsibility, the insurer’s response, and whether negotiations resolve the dispute or litigation becomes necessary. No particular schedule or result can be promised.
slip and fall practice page and its related premises liability page. The pages address related premises matters; which issues apply depends on the facts.
How can the property’s management or control affect the investigation?
Responsibility for a property area may not be obvious from the name on a sign or the building’s appearance. One entity may own the property, another may operate a business there, and another may perform cleaning or maintenance. A lease, service arrangement, or division of duties could matter, but the existence and relevance of any such arrangement must be established from the circumstances.
Suppose a fall occurs in a shared entryway at a commercial building. The tenant may control its storefront, a building manager may handle common areas, and a contractor may perform scheduled cleaning. That example does not mean all three are responsible. It shows why the investigation may need to ask who managed the specific location, who performed relevant tasks, and what each person or entity knew.
Similarly, a fall in a parking area may raise different questions from a fall inside a business. The location might be maintained by the business, a property owner, a municipality, or a contractor, depending on the arrangement and facts. A witness may know who was working nearby but not who had responsibility for inspection. Documents and interviews can take time to identify and evaluate.
Clarifying these roles can affect both the direction and pace of a claim. If an insurer initially responds for one entity but another party may have a role, the parties may need to identify the proper participants and applicable coverage. That does not establish that any particular person or company is legally responsible. It means that the right questions may not be apparent from the first report alone.
What happens when liability is disputed?
A property owner, operator, or insurer may question whether a dangerous condition existed, who was responsible for it, whether there was notice, or how the incident occurred. The parties may also disagree about whether the condition caused the reported injury. Each open question can lead to requests for more information, interviews, or additional review.
Responsibility can involve several factual questions. Imagine a person reports slipping on a liquid near a doorway. The person recalls seeing it only after the fall. A nearby worker recalls cleaning the area earlier but does not know when the liquid appeared. A photograph taken later shows a damp floor but no clear source. Those accounts may all contribute information, yet none alone answers every question about timing, notice, or control.
Another example is a change in the description of the location. An initial report may identify a general area, while a later diagram or photograph places the fall near a particular entrance. That difference may be innocent, but it may require clarification before the parties can assess which records, employees, or camera views matter. The time required to resolve ambiguity depends on the available information and the responses to follow-up.
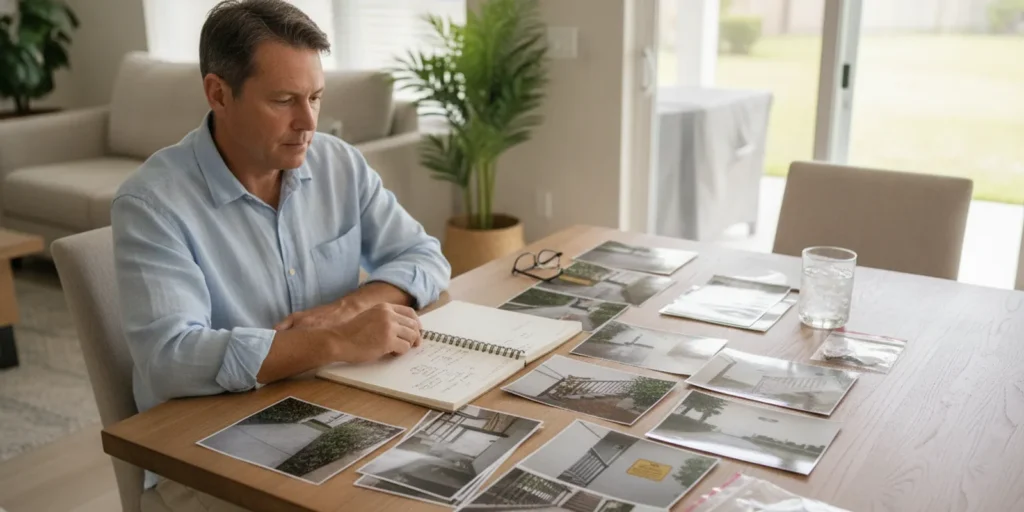
It is useful to separate what is known from what is assumed. Write down the date, time, and location while memory is fresh. Identify who was present and what each person personally observed. Keep original photographs and messages. If an incident report was made, note when and where it was submitted and retain any copy you receive. Do not change a record to make it appear more certain or present a guess as a confirmed fact.
Disagreement does not automatically mean a claim will fail or proceed to court. It does mean that the parties may need more information before they can decide whether to negotiate and on what terms. A disputed point may be resolved through additional evidence, remain unresolved, or be considered within formal litigation. The path cannot be predicted from the existence of a disagreement alone.
How can the insurer’s response change the pace?
After a claim is reported, an insurer may acknowledge the report, ask questions, request records, investigate the scene, or seek statements. It may need to identify the policy, the insured party, or the coverage period. The response can be affected by how quickly information is available and whether the insurer accepts, disputes, or needs to investigate an issue.
A quick acknowledgment is not the same as an agreement on responsibility or settlement. A request for additional material does not, by itself, reveal the final decision. It may mean that the insurer is gathering information, or it may signal that a particular issue remains disputed. The significance of a communication depends on its wording and context.
Responses can also involve several steps rather than one decision. A representative may request documents, review what is supplied, ask a follow-up question, and then communicate a position. If a document is missing or a question is unclear, the exchange may pause while the information is located or explained. The more parties or policies involved, the more coordination may be needed.
Keep a simple communication log with the date, the name or department, what was requested, what was sent, and any stated next step. Save letters and emails, note the claim identifier, and retain copies of material provided. If you speak by phone, write a short factual note soon afterward. This creates an organized history if there is later uncertainty about what was requested or when it was answered.
If you do not understand a request, ask what it concerns and whether a response date applies. Avoid guessing at facts or making statements about fault or injury that you cannot support. Do not treat an informal estimate from a representative as a guaranteed settlement date. Insurance policies and claim-handling circumstances differ, and no general guide can determine the meaning of a specific communication.
How do negotiations affect settlement timing?
Negotiations require the parties to evaluate information and communicate positions. They may exchange a demand, a response, supporting records, and questions about the incident or reported losses. A counteroffer can lead to further discussion, but a series of offers does not guarantee an agreement.
For instance, one side may believe more information is needed about the condition of the property, while the other may believe the existing photographs and reports are enough to discuss resolution. The parties may then exchange additional records or explain why they view the evidence differently. That exchange can take time, especially if records must be collected from multiple sources or a disputed point requires investigation.
Negotiations can pause while a party gathers documents, reviews evidence, or seeks clarification. They may also slow if the parties disagree substantially about responsibility, the injury, or the terms of a resolution. A delay in communication does not necessarily mean that a claim has been rejected, and a new offer does not necessarily mean that it will settle. The parties’ actions and the specific terms matter.
Before accepting a proposed resolution, understand the written terms and what claims they cover. A release or other settlement document can have important consequences, including language about whether claims are ended. Do not rely on a general article to decide whether to sign. The implications depend on the document and the facts, and an attorney can review them for a particular situation.
It can help to distinguish negotiation activity from resolution. An insurer may be reviewing a claim while the parties have not agreed. They may exchange numbers without agreeing on a release. They might agree on some terms but still need documents or signatures before the matter is complete. Ask what step is pending rather than assuming that any offer or verbal discussion marks the end of the process.
Why can litigation take longer?
If a matter does not resolve through claim discussions, a lawsuit may be considered. Litigation involves formal procedures, court schedules, and deadlines. Depending on the case, the process can include pleadings, discovery, depositions, motions, conferences, settlement discussions, and trial preparation. Which steps apply and how long they take vary with the issues, parties, court schedule, and procedural requirements.
Discovery is a formal process for obtaining relevant information. It may involve written questions, requests for documents, and depositions. The parties may need time to prepare responses, locate records, coordinate schedules, or resolve disputes about requests. If the evidence concerns several entities or a range of records, the volume of information may add work. This description is general and does not predict what a particular lawsuit would require.
Motions or other disputes can also affect the schedule. A party may ask the court to decide a legal or procedural issue, and the court controls when and how it is considered. Court calendars are not controlled by either party alone. If a hearing or trial date changes, the overall timeline can change as well.
A lawsuit does not automatically produce a quick settlement, and filing one does not guarantee a trial or a particular outcome. Parties may continue discussing resolution during litigation, but formal procedures can add time and uncertainty. Whether litigation is appropriate is a legal decision that requires advice based on the specific matter.
Deadlines can affect legal rights, and applicable rules can depend on details such as the parties and circumstances. Do not use a general online timeline to calculate a filing date. If you have a possible claim, promptly ask a licensed attorney to review the facts and the deadlines that may apply. This guide does not state a deadline or replace that review.
What can make a claim move more smoothly?
No person can control every insurer, provider, property manager, witness, or court step. Still, organized information may help reduce avoidable confusion. “Moving smoothly” does not mean rushing a decision or sacrificing important questions. It means making it easier to identify what is known, what is missing, and who may need to respond.
Start with a one-page incident timeline. Include the date and approximate time, the address or specific part of the property if known, the condition you recall, what happened immediately before and after the fall, and the names of people you contacted. Mark uncertain details as estimates. If your memory changes or you find a document that clarifies something, add a dated note rather than silently rewriting the original record.
Next, make a document inventory. Record which photographs you have, where they are stored, and whether they are original files. List any incident report, correspondence, medical records, bills, insurance letters, or witness contact details. For each item, note whether it is in your possession, was requested, or is still outstanding. This simple inventory can prevent repeated searches and make it easier to answer a specific request.
Then use a communication log. Record the date, person or organization contacted, method, short description, and any stated next step. If a representative says to expect an update, note the date mentioned without treating it as a binding settlement promise. If an update does not arrive, the log helps you make a focused follow-up inquiry instead of repeating the entire story.
Keep records in a secure, consistent place. A paper folder can work; so can a clearly named digital folder. Avoid scattering important items across text messages, email accounts, and photo libraries without an index. Retain copies of what you provide, and do not send original records unless advised and appropriate. If you receive a new document, record when it arrived and what issue it appears to address.
These organizational steps cannot create missing evidence, determine legal responsibility, or compel an insurer to respond by a certain date. They can help keep factual details accessible and make a conversation more specific. The value is clarity, not a promise of faster settlement.
What should you do while waiting for an update?
Waiting can be frustrating, especially when there are medical appointments, work concerns, or questions about bills. Separate the matters you can manage from the decisions that depend on another person. You can keep personal records organized, note new information, and ask what the next requested step is. You cannot make an insurer accept a position, make a witness respond, or control the court’s schedule.
A useful waiting checklist might include:
- A brief incident timeline, with dates and uncertainty clearly marked.
- Photographs, video, witness details, and any incident report or related correspondence.
- Medical visit information, bills, and records you have received.
- Insurance letters, claim identifiers, information requests, and copies of your responses.
- A dated record of calls and conversations, including any next step mentioned.
- A list of unanswered questions, such as which document is pending or who is expected to respond.
When you follow up, make the question narrow and practical. For example: “I sent the requested incident report on Tuesday. Can you confirm it was received and let me know whether another item is needed?” This approach does not pressure anyone to reach a particular result, but it helps clarify the status of a specific exchange. Keep a copy of the follow-up and any response.
If you receive a new form, authorization, offer, or release, do not sign or accept solely because you feel that waiting has gone on too long. Read what is being requested and consider seeking legal advice about the consequences. A prompt review is not a guarantee that the matter will resolve by a particular date; it is a way to understand the decision in front of you.
What examples show why the timelines can differ?
Examples can make the variables easier to see, provided they are not treated as predictions. The following hypothetical situations illustrate different sources of delay and do not describe a particular client or promise an outcome.
Example one: clear location, but records are still being gathered
A person slips near a store entrance and reports the fall. A photograph taken soon afterward shows the general area, and a witness provides contact information. The person is still attending follow-up appointments, while separate records and bills are being collected. The location may be relatively clear, but the medical and documentary picture is still developing. The parties may decide to wait for more information or discuss what is available; the example does not establish which choice is right.
The practical lesson is to avoid equating strong documentation of one issue with a complete claim file. A photograph may help identify the place and condition, but it does not necessarily answer every question about notice, control, injury, or losses. The next useful step may be identifying which records remain outstanding and whether they matter to the parties’ evaluation.
Example two: the event is reported, but notice is disputed
A person reports falling on a wet surface. The property representative says the area was inspected shortly before the incident, while the injured person recalls seeing no warning sign. The parties may need to clarify when the inspection happened, who performed it, what area it covered, and whether other records or witnesses exist. The dispute may take additional time because the central question is not simply whether a fall occurred, but what the available evidence shows about the condition and its timing.
The practical lesson is to preserve specific observations and avoid overstating what they prove. A person can describe what they saw, where they were, and when they noticed it. Whether that information establishes a legal point is a separate question for case-specific review.
Example three: more than one entity may have a role
A fall happens in a shared area between a business and a larger property. The business takes an incident report, but it is not clear who handled cleaning or inspection. The parties may need to identify the property manager, maintenance provider, or other relevant participant. That information can affect whom to contact and what records to request. It does not mean that every entity identified is responsible.
The practical lesson is that ownership, operation, and maintenance can be different roles. A claim may require careful identification of the relevant people and records before meaningful discussions can proceed. The first company a person contacts may not have every answer.
Example four: negotiations begin but stop for clarification
The parties exchange positions, but an insurer asks a question about a medical record or the location shown in a photograph. The discussion pauses while the question is answered. Once the information is provided, the parties may resume negotiations, ask another question, or continue to disagree. A pause is a process event, not a reliable signal that a settlement is imminent or impossible.
The practical lesson is to ask which issue is currently unresolved. “What are you waiting for?” is often less useful than identifying a particular record, fact, or review step. If the request is confusing or raises legal concerns, obtain appropriate advice rather than guessing.
Example five: an unresolved dispute leads to formal proceedings
The parties remain apart on responsibility or other important issues after claim discussions. A lawsuit may be considered, which introduces court filings, formal information exchanges, and scheduling. The process could still include settlement discussions, but the timeline now depends in part on procedural steps and court availability.
The practical lesson is that litigation is not just a longer negotiation. It has rules, responsibilities, and deadlines that require attorney guidance. A person should not infer from this example whether filing is advisable or how long any specific case would take.
What should you ask during a case review?
A free case review can be an opportunity to explain what happened and ask what information may be relevant. A focused conversation can distinguish confirmed facts from unanswered questions. Consider preparing a short timeline and a list of questions such as:
- What facts remain unclear about the location, condition, or timing?
- What evidence do I have, and what evidence may need to be identified or preserved?
- Are there other people or entities whose role may need to be examined?
- What records might help explain the incident or the treatment that followed?
- What should I understand about communications or documents from an insurer?
- What next steps depend on facts that have not yet been confirmed?
- Which deadlines should an attorney review for my situation?
- If there is an offer or release, what does the document say it would resolve?
These are prompts, not a checklist that decides whether a claim will succeed. An attorney must assess the specific facts and applicable law. A consultation or inquiry does not itself create an attorney-client relationship; an engagement generally requires a written agreement. If you want to learn more about the firm, you can review its about page and its answers to common personal injury questions.
Frequently asked questions
Can a slip and fall settlement happen before treatment ends?
Discussions may occur while care is ongoing, but whether resolution makes sense depends on the facts and proposed terms. The medical picture may not yet be complete, and a signed settlement may affect future claims. Discuss the consequences of a proposed agreement with an attorney before accepting it.
Does a quick insurer response mean the claim will settle quickly?
No. An acknowledgment or request for information is not the same as agreement on responsibility, losses, or settlement terms. The parties may still need to investigate, review records, and negotiate.
Will every slip and fall claim go to court?
No. Some disputes may resolve without a lawsuit, while others may involve litigation or may not settle. The path depends on the circumstances and the parties’ positions. No general article can predict what will happen in a particular claim.
Can anyone give me an exact settlement date?
A general description cannot establish an exact date. Treatment, evidence, notice, responsibility questions, insurer response, negotiation, and court procedures may affect timing. A case-specific review can discuss known steps and uncertainties without guaranteeing a schedule.
Does asking an insurer for an update make a settlement happen sooner?
A focused follow-up can clarify whether a particular document or review is pending, but it cannot compel a decision or guarantee a faster resolution. Keep a record of your inquiry and the answer, and ask an attorney about legal questions or documents you do not understand.
What is a practical next step?
If you were hurt in a fall, focus first on your health and preserve information you can safely access. Keep a factual timeline, organize records, and note what remains unknown. A case-specific review can help identify the next questions without promising that a claim will settle or predicting when. You can also review the firm’s listed South Florida service-area information as you prepare questions.
No general timeline can predict when a particular slip and fall claim will resolve, so seek advice based on your own facts and do not rely on this article as legal advice.